


Tax & Finance
 Post
Lost Goods VAT Decision Guide: When Must VAT Be Corrected?
When must VAT on lost goods be corrected, and when does the deduction stay in place? A five-question decision flow, fixed-asset proportioning, and the document checklist.
 Post
VAT on Destroyed Goods: Why Do the Tax Office and the Council of State Disagree?
The tax administration treats expired, destroyed goods as lost goods; the Council of State's 9th Chamber does not. Both views, the numerical difference, and the documents required for each path.
Communiqué on the Destruction Rate
Tax Procedure Law General Communiqué (Series No: 496) under Law No. 213 was published in the Official Gazette dated 25 May 2018, No. 30431, and is commonly called the “Destruction Rate Communiqué”. It deals with two matters together: the general rules on valuing goods that must be destroyed under Article 278 of the Law, and […]
Destruction Rate Application Form
The Destruction Rate Application Form is EK 1 of the Tax Procedure Law General Communiqué (Series No: 496) under Law No. 213, published in the Official Gazette dated 25 May 2018, No. 30431. The form is used in an application to the Revenue Administration to benefit from Article 278/A of the Tax Procedure Law and […]
Annual Destruction Rate Tracking Form
The Annual Destruction Rate Tracking Report is EK 2 of the Tax Procedure Law General Communiqué (Series No: 496) under Law No. 213, published in the Official Gazette dated 25 May 2018, No. 30431. Taxpayers who benefit from a set destruction rate use this report each year to tell the Revenue Administration how the rate […]
 Post
Unsold Electronics Disposal: Stock, Brand, and Tax
Holding obsolete, returned, or damaged electronics is risky, and so is selling them cheap. The right order: official valuation, a licensed facility, and records.
Tax Procedure Law Article 278 — Valuation of Goods That Have Lost Value
What does Article 278 of the Tax Procedure Law regulate? Article 278 of the Tax Procedure Law No. 213 (published in the Official Gazette issues 10703, 10704 and 10705 of 10, 11 and 12 January 1961) is titled "Goods that have lost value" and sits among the valuation provisions. It provides that goods whose economic […]
Tax Procedure Law Article 278/A — Direct Expensing of Goods to Be Destroyed
What is Article 278/A and when was it added? Article 278/A of the Tax Procedure Law No. 213 is titled "Goods that must be destroyed". It was added to the Tax Procedure Law by Article 10 of Law No. 7103 of 21 March 2018, which was published in the Official Gazette of 27 March 2018 […]
VAT Law Article 30/c — VAT on Lost (Zayi) Goods
What does Article 30/c of the VAT Law say? Article 30 of the Value Added Tax Law No. 3065 of 25 October 1984 (Official Gazette of 2 November 1984, issue 18563) lists the taxes that cannot be deducted from calculated VAT. Paragraph (c) states that VAT on lost goods cannot be deducted, except for goods […]
Tax Procedure Law Article 278 and Law No. 7103: Tax Treatment of Destroyed Goods
Goods that are destroyed are dealt with in tax law under three separate provisions: Article 278 of Tax Procedure Law No. 213 (VUK), Article 278/A added by Article 10 of Law No. 7103 of 21 March 2018, and Article 30(c) of Value Added Tax Law No. 3065. Law No. 7103 was published in the Official […]
 Post
Can the Cost of Lost Goods Be Expensed?
How are the cost of lost goods and the corrected VAT treated for income and corporate tax? A summary table by cause of loss, covering theft and insurance indemnity.
 Post
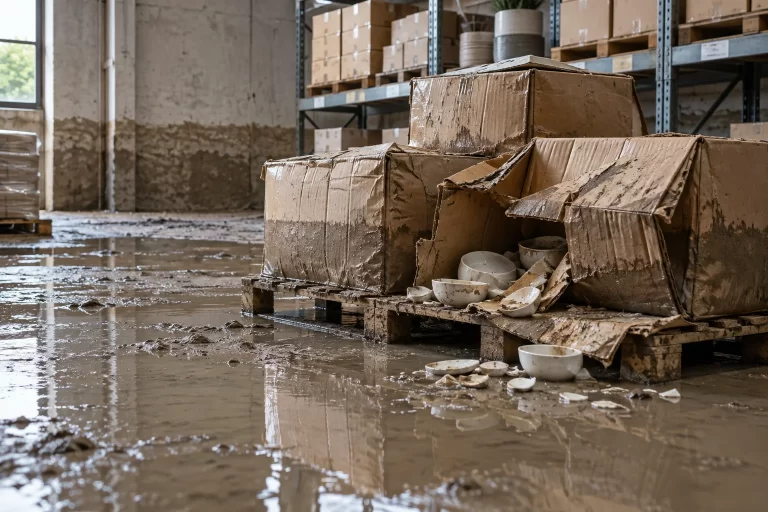
Goods Lost in Earthquake, Flood, and Fire: The Limits of the VAT Exception
No VAT correction is needed for goods lost in an earthquake, a flood, or a declared fire. But an ordinary fire does not qualify, and fixed assets follow a different rule in practice.